
COMMERCIAL PROPERTY LOANS BRISBANE SOUTHSIDE
Own the premises your business runs from.
Offices, warehouses, shops and mixed-use property are assessed on different rules to a home loan. We structure commercial finance across banks and non-bank lenders, separate from your personal lending.
Francesco Mercati
“Gundeep was FANTASTIC in getting me across the line on my first home, can't recommend him more!! Chat to us here.
Evergreen is here to help with your Commercial Property Loan.
Welcome to Evergreen Loan Solutions, where we are dedicated to empowering individuals and families to achieve their Commercial Property Loan goals with confidence and clarity. Established with a vision to provide personalised financial solutions, Evergreen Loan Solutions has been a trusted partner for clients seeking tailored guidance in navigating the complexities of the financial landscape.
Our Story.
Led by Gundeep Virk, a seasoned banking professional with over 15 years of experience in various roles including home loans, unsecured loans, agri-banking, and branch leadership, Evergreen Loan Solutions is dedicated to providing personalised financial solutions.
Our team take the time to listen and tailor our services to you, providing expert guidance every step of the way.
1. Owner-occupied or investment.
Finance for premises you operate from, or commercial property held as an investment, each set up on its own terms.
2. Business and property presented together.
Commercial lenders look at your business financials as well as the building. We present both the way each lender wants to see them.
3. SMSF purchases considered.
Buying business premises through your super fund is a common strategy. We arrange the lending while your accountant advises on the fund.
Let us research 50+ banks & lenders to find the right solution for you.
We work with Australia’s leading banks and non-bank lenders including ANZ, Bank of Queensland Suncorp, AMP, Macquarie Bankwest and many more, giving you more options, better rates, and loans tailored to your exact needs. No bias, just what works best for you.
How our Brisbane Southside mortgage broker helps
Why do Brisbane Southside business owners use Evergreen for commercial property?
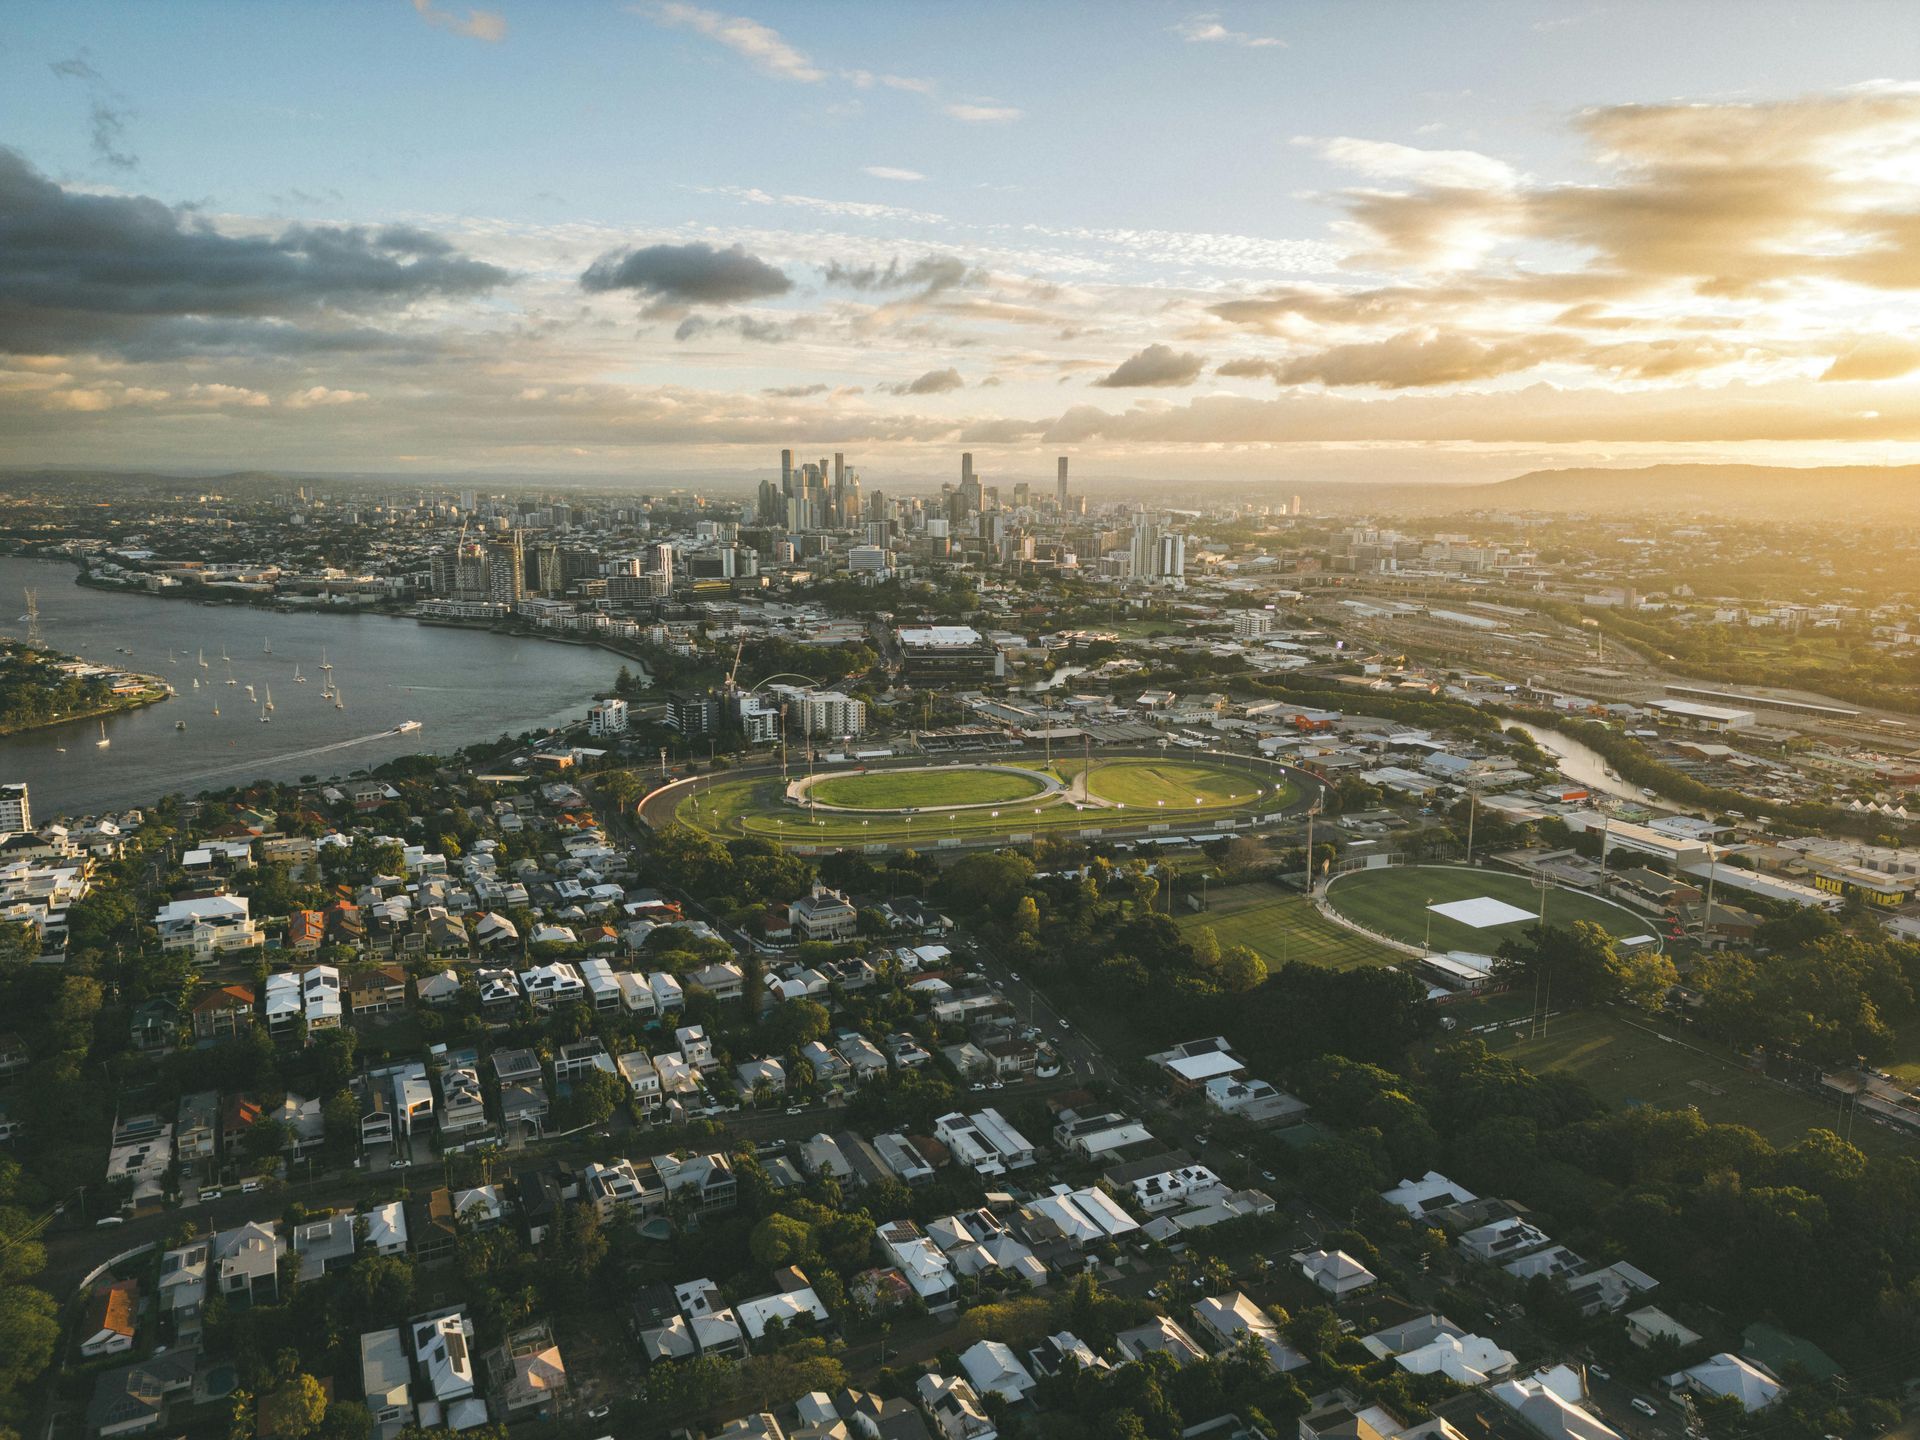
Commercial stock on the Southside is varied: offices around Brisbane Technology Park, industrial units in Rocklea, Archerfield and Coopers Plains, and retail along the Sunnybank and Logan Road corridors. Lender appetite differs for each.
Commercial policy varies more between lenders than residential does, particularly on deposit, loan term and how the lease or your business income is assessed. We tell you what is achievable before you make an offer.
Book a free chat to find out more.
Brisbane Southside mortgage broker reviews
“Evergreen Loan solutions have been very helpful throughout our journey. I want to thanks Gundeep for the support all through this journey of buying a house.
Evergreen home solutions has always been very professional and always guided us to realise our dream house."
Monika Goel
June 2026
★★★★★
5.0 star Google reviews
FAQs
How is a commercial property loan different from a home loan?
Terms are usually shorter, often up to 15 to 25 years, deposits are larger and rates are generally higher. The lender assesses the lease, the tenant's strength or your business financials alongside the property itself. Some commercial loans also have periodic reviews. Because policy varies so much, comparing lenders makes a bigger difference than with a home loan.
How much deposit will I need?
Generally more than for a home. Many lenders want a deposit of around 20% to 30% or more, depending on the property type, location and whether you will occupy it or lease it out. Specialised properties can need more. Equity in your home can sometimes be used instead of cash. We confirm the figure for your purchase early, before you sign a contract.
Can I buy the premises my business operates from?
Yes. Owner-occupied commercial lending is one of the most common uses, replacing rent with repayments on a property you own. Lenders assess your business's ability to pay, and some allow lower deposits for owner-occupiers. You may also buy through a company, trust or SMSF. Read about commercial property loans for business owners.
Will commercial finance limit my home borrowing?
It can if it is not structured carefully. Lenders may count the commercial loan and any guarantees against your personal borrowing. Where the property's rent or your business covers the repayments, some lenders set it aside. We structure it so it is assessed on its own merits wherever possible and plan the timing with any home loan you need.
Can I use my home equity to buy commercial property?
Often, yes. Equity in your home can fund the deposit and costs, either as a separate loan or as additional security. This can reduce the cash you need, but it also puts your home at risk if the commercial investment struggles. We explain the options and structure the loans so the two properties stay as independent as possible.
How long does commercial finance approval take?
Usually longer than a home loan, often three to six weeks, because lenders need a commercial valuation, lease details and business financials. Complex properties or large loans can take longer. We recommend allowing enough time in your contract's finance clause and preparing your documents before you make an offer, so you do not risk losing your deposit.




