
DOWNSIZING HOME LOANS BRISBANE SOUTHSIDE
Downsize on your timeline, with the numbers clear before you list.
Downsizing should free up equity, not create a scramble. We map what you will walk away with, and arrange any finance needed to secure the next place before the family home sells.
Francesco Mercati
“Gundeep was FANTASTIC in getting me across the line on my first home, can't recommend him more!! Chat to us here.
Evergreen is here to help with your Downsizing Home Loan.
Welcome to Evergreen Loan Solutions, where we are dedicated to empowering individuals and families to achieve their Downsizing Home Loan goals with confidence and clarity. Established with a vision to provide personalised financial solutions, Evergreen Loan Solutions has been a trusted partner for clients seeking tailored guidance in navigating the complexities of the financial landscape.
Our Story.
Led by Gundeep Virk, a seasoned banking professional with over 15 years of experience in various roles including home loans, unsecured loans, agri-banking, and branch leadership, Evergreen Loan Solutions is dedicated to providing personalised financial solutions.
Our team take the time to listen and tailor our services to you, providing expert guidance every step of the way.
1. Later-life income assessed fairly.
Lenders differ a great deal on retirement, part-time and investment income. We place your application with one whose policy fits your situation.
2. The next property checked first.
Moving to a unit or townhouse? Some lenders apply tighter policy to smaller apartments, so we check the address before you make an offer.
3. A bridge if you need one.
Bridging finance lets you buy the right place first and sell the family home without rushing.
Let us research 50+ banks & lenders to find the right solution for you.
We work with Australia’s leading banks and non-bank lenders including ANZ, Bank of Queensland Suncorp, AMP, Macquarie Bankwest and many more, giving you more options, better rates, and loans tailored to your exact needs. No bias, just what works best for you.
How our Brisbane Southside mortgage broker helps
Why do Brisbane Southside downsizers use Evergreen?
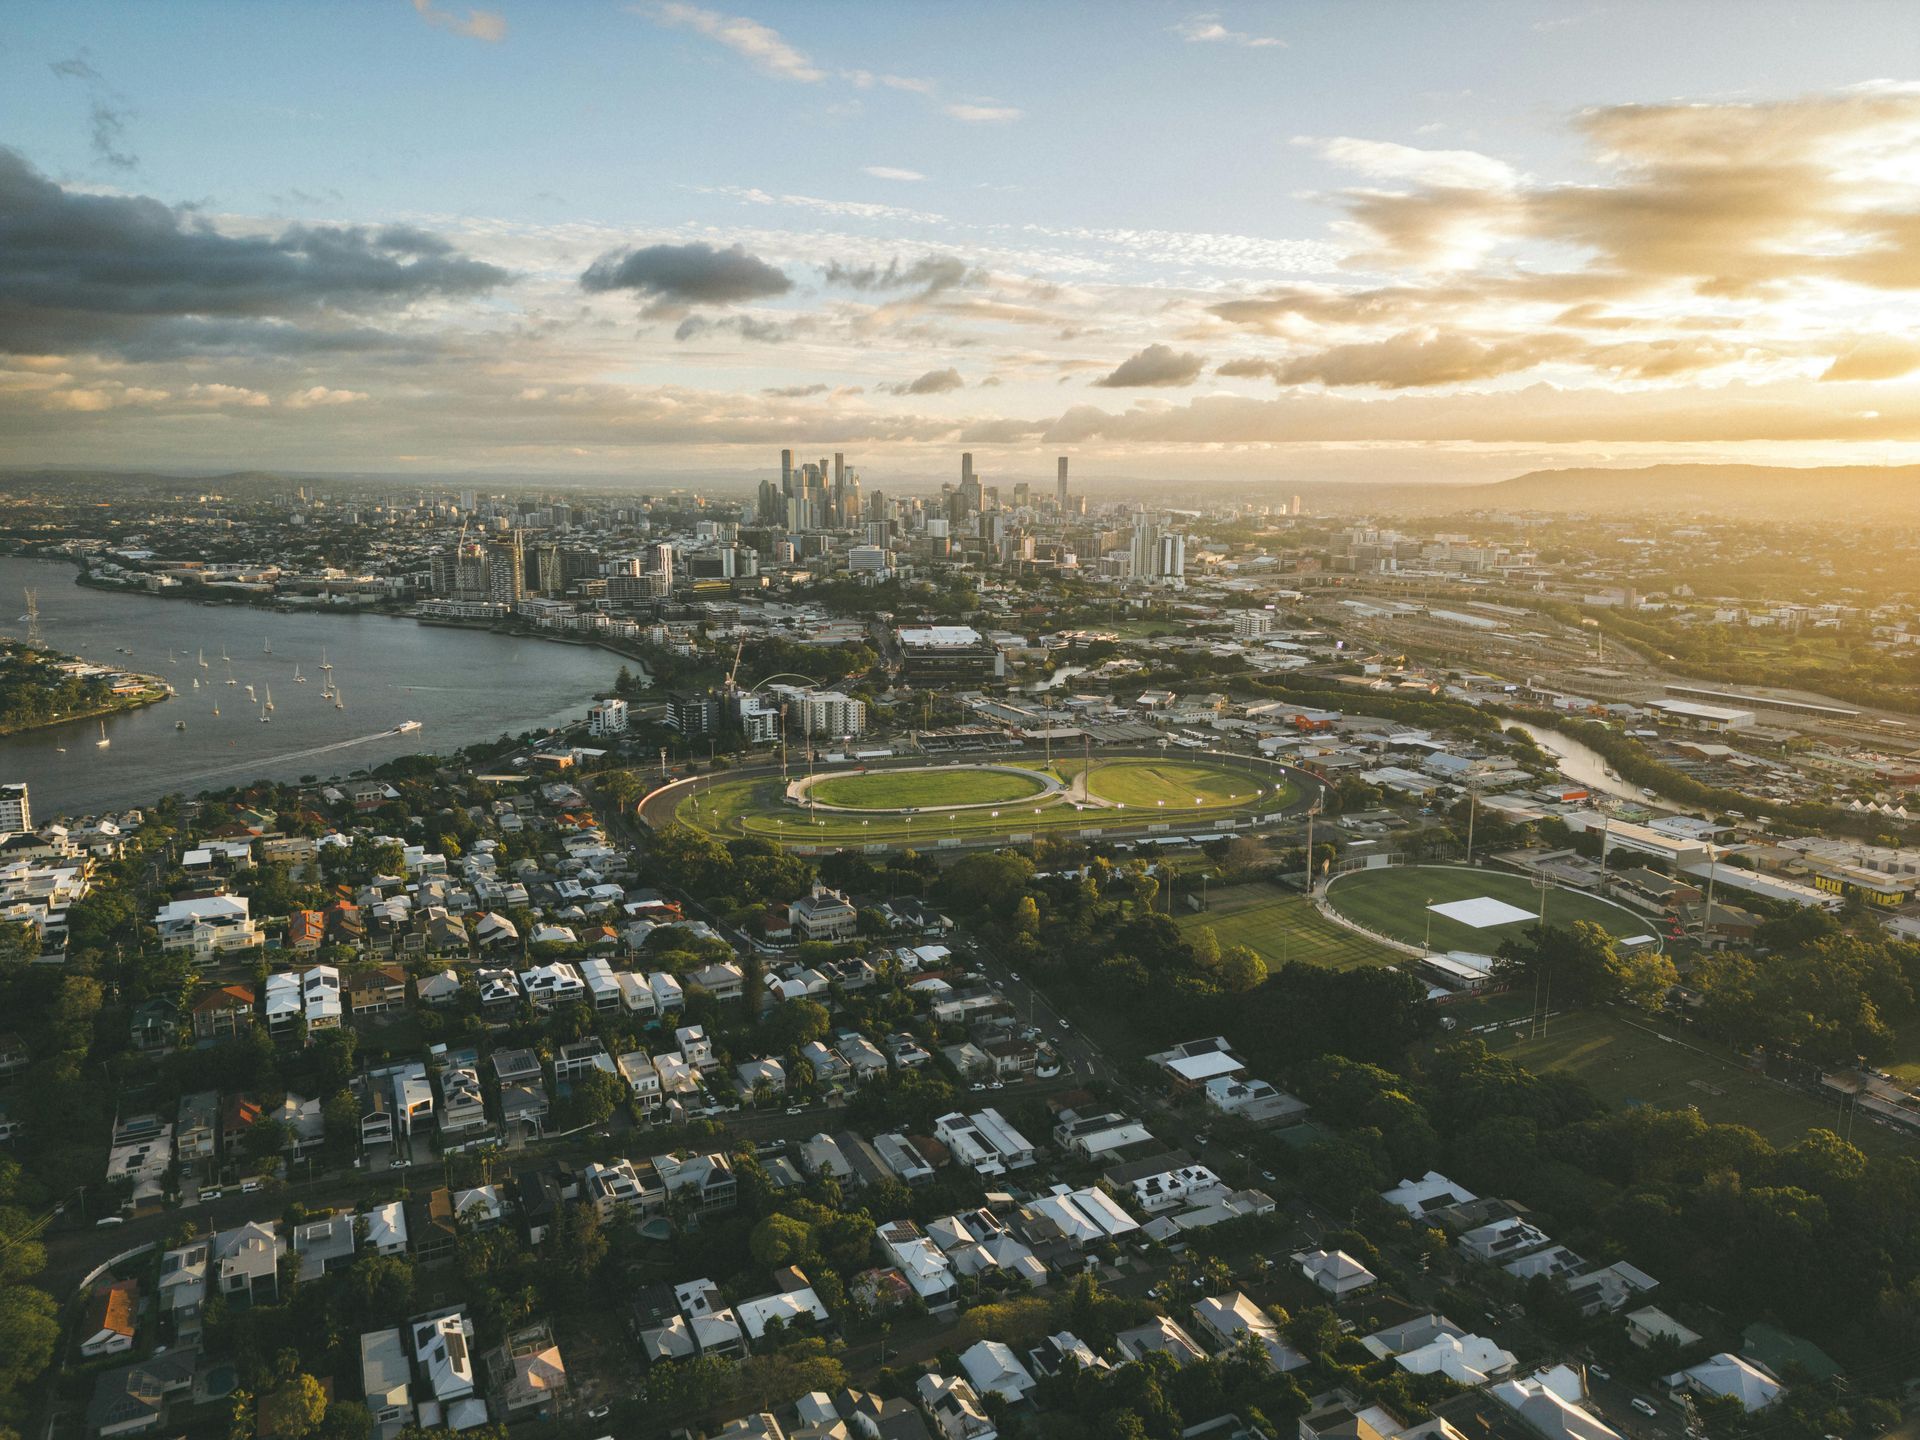
Downsizers on the Southside often stay local, moving from a family home in Mansfield, Wishart or Robertson to a low-maintenance townhouse or unit near Sunnybank, Upper Mount Gravatt or the Eight Mile Plains busway.
Lender policy on exit strategy and income later in life varies widely, and it usually decides the application more than the rate does. We compare 50+ lenders and explain every step without jargon or pressure.
Book a free chat to find out more.
Brisbane Southside mortgage broker reviews
“Evergreen Loan solutions have been very helpful throughout our journey. I want to thanks Gundeep for the support all through this journey of buying a house.
Evergreen home solutions has always been very professional and always guided us to realise our dream house."
Monika Goel
June 2026
★★★★★
5.0 star Google reviews
FAQs
Can I get a loan if I am retired or semi-retired?
Often, yes. Lenders look at your income sources, such as superannuation pensions, investments, rent or part-time work, and want a clear exit strategy showing how the loan will be repaid. Policy on age and exit strategies differs significantly across our panel, so the right lender matters. Read about downsizing home loans.
Should I buy before I sell?
It depends on your equity and the market. Buying first lets you secure the right home without rushing, and bridging finance can cover the gap until your current home sells. Selling first gives certainty on your budget but may mean renting. We model the cost of a bridge before you commit, so you can choose with the numbers in front of you.
Does moving into an apartment change the finance?
It can. Some lenders restrict lending on very small units, high-density buildings or certain postcodes, and may ask for a larger deposit. Body corporate fees are also counted as a living expense. If you are buying with little or no loan, this matters less. We check which lenders will fund the apartment before you make an offer.
What costs come off my sale proceeds?
Agent commission, marketing, legal or conveyancing fees, any loan payout and break costs, and then transfer duty, legal fees and moving costs on your next purchase. Together these can be a significant amount. We map the full picture before you list, so you know how much will be left to put towards your next home or keep in savings.
Can I use the downsizer contribution to super?
If you are eligible, the downsizer contribution lets you put up to $300,000 per person from the sale of your home into superannuation, outside the usual contribution caps. Age and ownership conditions apply. This is a financial advice question, so speak with your financial adviser or accountant, and we can arrange any finance you need around it.
Can I downsize without a loan at all?
Often, yes. If your sale proceeds cover the new home and costs, you may not need finance. Many downsizers still use a short bridging loan or a small loan for timing reasons, for example settling on the new home before the old one sells. We work out whether a loan helps and keep it as simple as possible.




